Kovo Credit Builder Review: How Does It Work?
The Kovo Credit Builder is designed for people who want to establish or strengthen their U.S. credit history without taking out a traditional loan or opening a conventional credit card. Kovo currently charges $10 per month for 24 months, reports payment activity to TransUnion, Equifax, Experian and Innovis, and says there is no hard credit inquiry, interest or additional fee for its Installment Credit Builder. It also bundles credit monitoring, identity protection and access to rewards.
That makes the product somewhat different from a traditional credit-builder loan. With a conventional credit-builder loan, the lender typically holds the borrowed amount in a savings account while the borrower makes payments and receives the funds after completing the loan. Kovo’s basic proposition is instead centered on creating a reported payment history through a $10 monthly installment plan.
How Does Kovo Credit Builder Work?
The basic Installment Credit Builder runs for 24 months at $10 per month, making the scheduled payments total $240 over the full term.
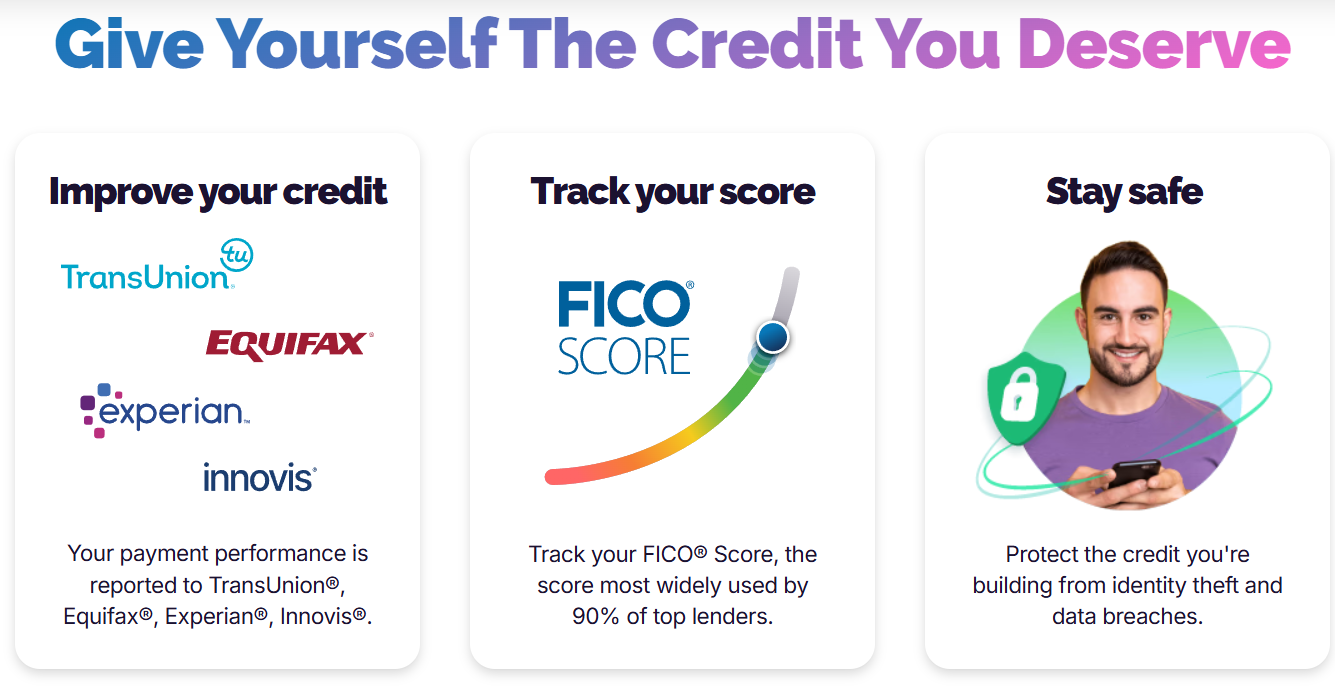
After approval, Kovo reports the account and payment performance to all four bureaus it lists: TransUnion, Equifax, Experian and Innovis. Kovo says there is no hard credit pull when applying and opening the account, although approval is subject to background verification and income qualification.
The process is essentially:
Apply → Get approved → Make $10 monthly payments → Payment history is reported → Monitor credit progress
The payment history is the key component. Kovo says on-time payments can positively affect credit, while late or missed payments can have a negative impact. It also explicitly states that a particular credit-score increase is not guaranteed because scores depend on information from multiple financial accounts and other factors.
What Do You Get for $10 a Month?
The Kovo Credit Builder isn’t just a payment-reporting account. The company says members also receive credit monitoring and identity protection during the credit-building period. Its current product information also includes rewards and credit boosts for eligible customers.
Here’s how the core offering looks:
| Feature | Kovo Installment Credit Builder |
| Monthly cost | $10 |
| Standard term | 24 months |
| Total scheduled payments | $240 |
| Hard credit inquiry | No |
| Interest | None |
| Additional fees | Kovo says none |
| Credit bureaus | TransUnion, Equifax, Experian, Innovis |
| Credit monitoring | Included |
| Identity protection | Included |
| Rewards | Available to eligible customers |
| Credit boosts | Available to eligible customers |
| Availability | U.S., including all 50 states and D.C. |
The absence of a hard inquiry is useful for someone who is concerned about adding another inquiry to a thin credit file. However, no hard pull doesn’t mean no credit consequences. The account itself becomes part of the reported credit history, and payment behavior matters.
Does Kovo Actually Improve Your Credit Score?
Source: KOVO
Potentially, but there is no universal number of points that Kovo can add.
- Credit scores are calculated from information in credit reports, and different scoring models can weigh information differently.
- Kovo itself warns that individual results vary and does not guarantee a score increase.
- The strongest case for a product like this is someone who has little or no established credit history and needs an account that can contribute positive payment history.
It is also important to keep expectations realistic.
- Opening Kovo does not erase existing late payments, collections or other negative information.
- A new account becomes one part of a broader credit profile.
And because late payments can work against you, the $10 monthly payment needs to be treated as a genuine financial obligation rather than a subscription that can be ignored.
Why Reporting to Four Bureaus Matters
Most consumers are familiar with the three major U.S. credit bureaus: Experian, Equifax and TransUnion. Kovo additionally reports to Innovis.
That broad reporting is one of the more distinctive parts of the product.
Still, reporting to four bureaus doesn’t mean every lender will use information from all four when evaluating an application. Different lenders and scoring models can use different credit-report sources.
The practical benefit is that Kovo is creating reported account activity across the bureaus it supports rather than limiting reporting to just one.
What Happens If You Miss a Kovo Payment?
This is one of the most important parts of the Kovo Credit Builder review. Kovo says late or non-payment can negatively affect your credit score.
That means the product shouldn’t be viewed as a risk-free way to generate positive credit history. The potential benefit comes from consistent payments, so someone who already struggles to keep up with recurring bills should consider whether another monthly obligation makes sense.
Kovo’s Help Center provides information about missed payments, automatic payments, payment methods, cancellation and early account closure.
Kovo’s Other Credit-Building Product
Source: KOVO
Kovo also offers a Revolving Credit Builder to eligible members. Unlike the $10 Installment Credit Builder, this is a revolving credit line that can be added by qualifying members. Kovo says both products report to four bureaus and include credit monitoring.
This distinction matters because installment and revolving accounts work differently in a credit profile. Someone considering Kovo should therefore look at the specific product being offered rather than treating every Kovo feature as the same type of account.
Rewards and Credit Boosts
Kovo has added incentives around its credit-building system. Its website currently advertises cash rewards of up to $1,225, including referral and other eligible rewards, and says eligible customers can unlock credit boosts after qualifying on-time payments.
These should be viewed as secondary benefits rather than the main reason to open the account. Eligibility requirements apply, and the advertised maximum isn’t the same thing as a guaranteed return for every member.
Is Kovo Worth Considering?
The Kovo Credit Builder is most relevant to people who need to establish or strengthen a credit profile and want a relatively straightforward monthly commitment.
Its clearest differentiators are the $10 monthly price, no hard inquiry, no stated interest or fees, four-bureau reporting, credit monitoring and identity protection.
The main limitation is equally straightforward: Kovo cannot guarantee how much your score will increase. Your broader credit history still matters, and missed payments can hurt rather than help.
At $10 a month, the financial commitment is relatively easy to understand: $240 over 24 months if every scheduled payment is made. Whether that cost makes sense depends on how much value you place on building reported payment history and the additional monitoring and protection features.
For anyone considering it, the most important step is to read the current terms before enrolling and make sure the monthly payment fits comfortably into the budget.
FAQs
1. How long does Kovo take to improve your credit?
There is no guaranteed timeframe or guaranteed number of points. Kovo states that results vary according to individual credit circumstances and other financial information.
2. Can Kovo hurt your credit?
Yes. Kovo states that late or non-payment can negatively affect your credit score.
3. Is Kovo available outside the United States?
No. Kovo says its service is currently available across all 50 U.S. states and the District of Columbia.
Also Read: Klover Review: Cash Advances Without Interest, What’s the Catch?